India’s 1st Startup Consulting Company Earns YouTube Silver Button
India’s 1st Startup Consulting Company Earns YouTube Silver Button
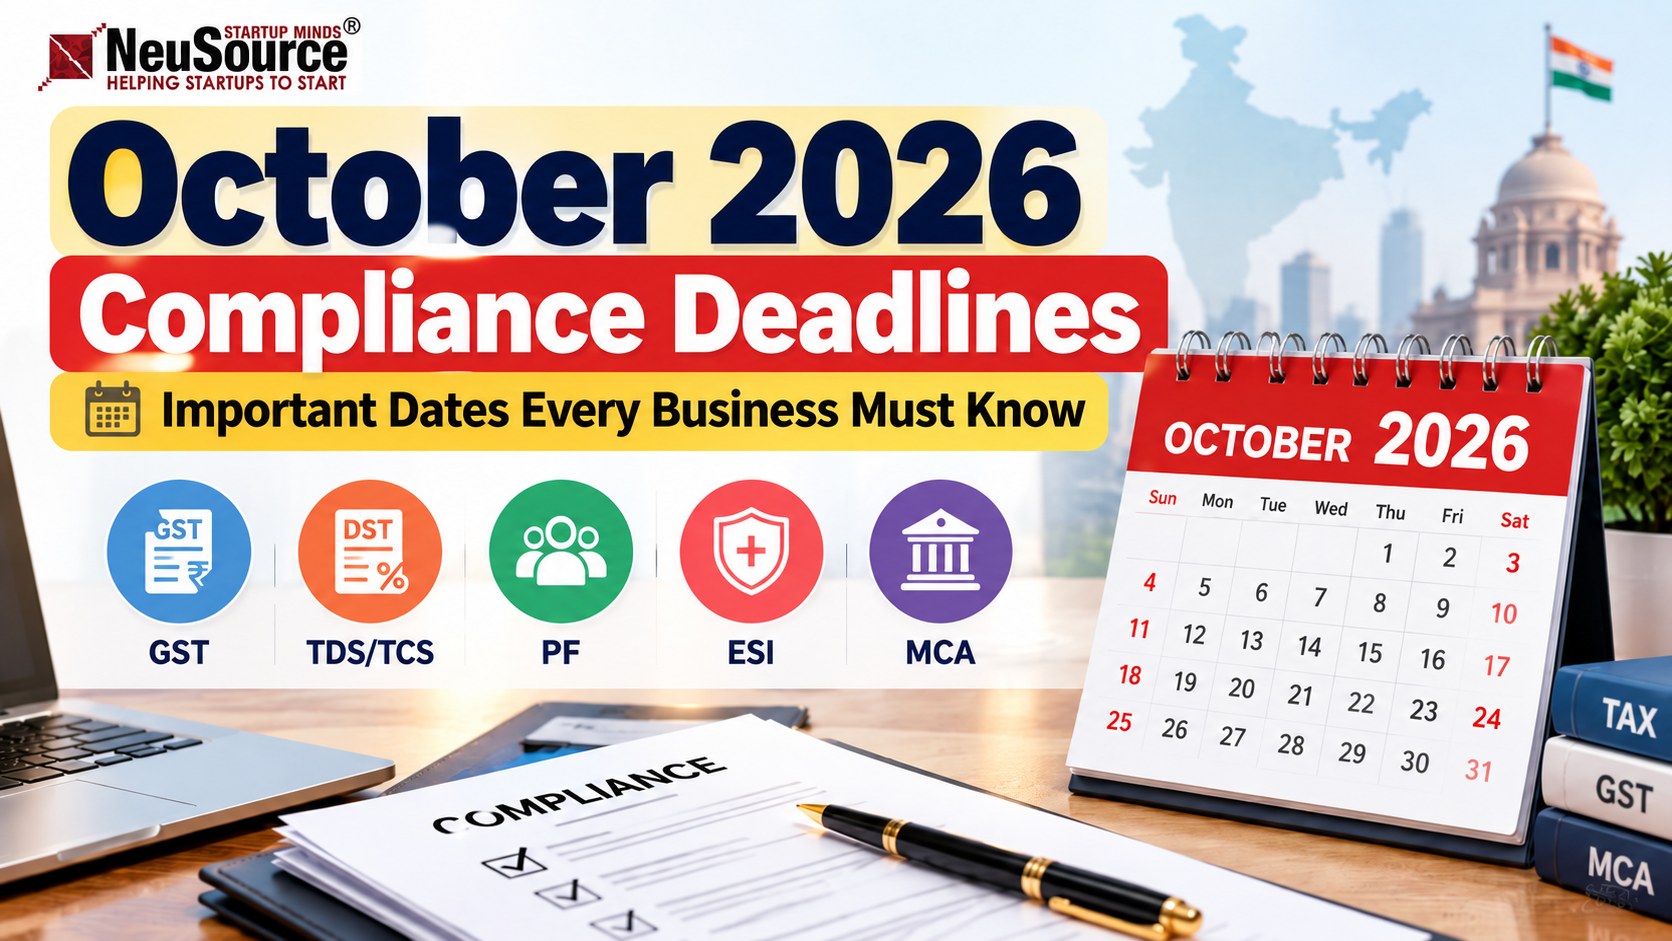
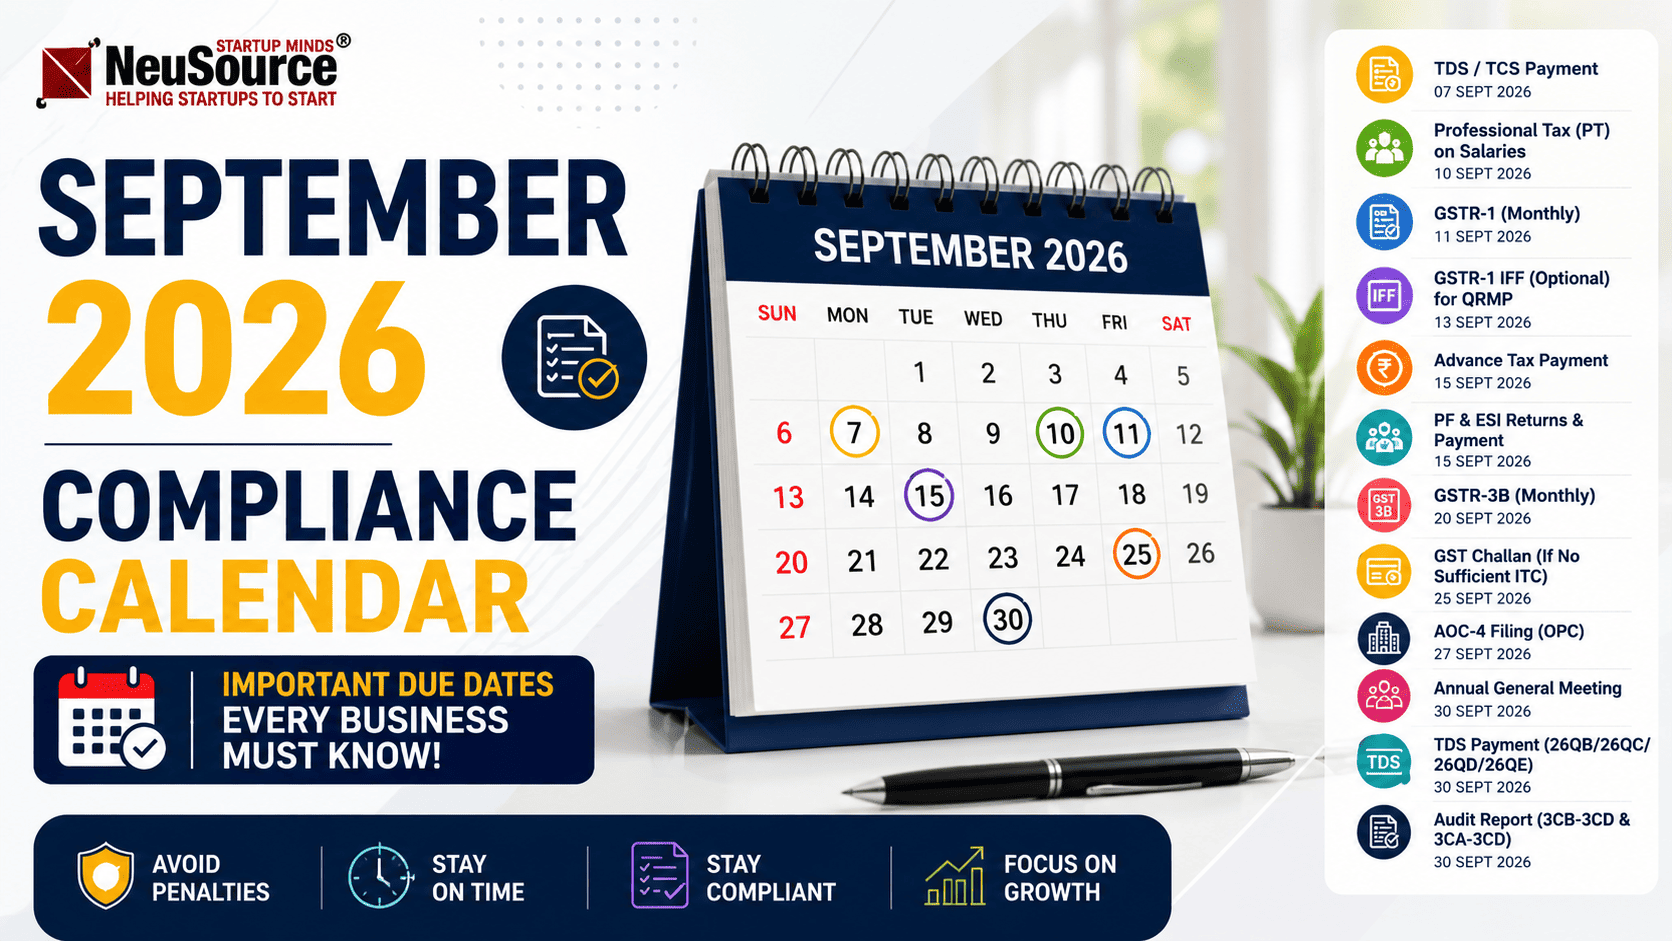
October 2026 is an important compliance month for startups, companies, LLPs, employers and other businesses in India.
Several monthly, quarterly and annual statutory obligations fall during the month, including GST returns, TDS and TCS compliances, PF and ESI contributions, tax audit reporting and important MCA and LLP filings.
Missing an applicable due date may result in interest, late fees, penalties, notices or other compliance complications.
To help founders, directors, finance teams, accountants and business owners plan ahead, here is the October 2026 Compliance Calendar covering key statutory dates and important applicability conditions.
| Due Date | Compliance | Applicable Period / Condition |
|---|---|---|
| 7 October 2026 | TDS/TCS Payment | September 2026 |
| 11 October 2026 | GSTR-1 – Monthly | September 2026 |
| 13 October 2026 | GSTR-1 – QRMP | July–September 2026 |
| 15 October 2026 | ADT-1 – Appointment/Reappointment of Auditor | Where auditor was appointed at a meeting held on 30 September 2026 |
| 15 October 2026 | TCS Return – Form 27EQ | July–September 2026 |
| 15 October 2026 | PF & ESI Contribution Payment | September 2026 |
| 18 October 2026 | CMP-08 | July–September 2026 |
| 20 October 2026 | GSTR-3B – Monthly | September 2026 |
| 21 October 2026 | Extended Tax Audit Report Due Date | AY 2026–27, for applicable taxpayers covered by CBDT extension |
| 22 October 2026 | GSTR-3B – QRMP Group 1 | July–September 2026 |
| 24 October 2026 | GSTR-3B – QRMP Group 2 | July–September 2026 |
| 30 October 2026 | AOC-4 – Financial Statements | Where AGM was held on 30 September 2026, subject to applicability |
| 30 October 2026 | LLP Form 8 | FY 2025–26 |
| 31 October 2026 | Quarterly TDS Statements – Forms 24Q, 26Q & 27Q | July–September 2026 |
| State-specific | Professional Tax | Due date varies according to applicable State law |
Important: Dates marked with an asterisk (*) are linked to the relevant meeting or event date and should not be treated as a universal deadline for every company.
Applicability may also vary based on entity type, GST filing frequency, state, turnover, registration status, AGM date and government notifications.
Businesses and other deductors that deducted tax during September 2026 should deposit the applicable TDS within the prescribed timeline.
Similarly, persons responsible for collecting applicable TCS should ensure timely deposit of the amount collected.
Before making payment, businesses should verify:
Late payment may attract applicable interest and other consequences under the Income-tax provisions.
Professional Tax should not be treated as having one common due date across India.
It is imposed and administered under State-specific laws. Accordingly, the payment date, return frequency, salary slabs and registration requirements can differ between states.
Businesses should verify:
A single nationwide Professional Tax deadline should not be assumed.
GST-registered businesses filing GSTR-1 monthly should prepare their outward supply details for September 2026.
Before filing, businesses should reconcile:
Accurate GSTR-1 reporting is particularly important because errors can affect the recipient's input tax credit and subsequent GST reconciliation.
Eligible taxpayers who have opted for the Quarterly Return Monthly Payment (QRMP) Scheme should track the quarterly GSTR-1 due date for the July–September 2026 quarter.
Under the normal QRMP schedule, quarterly GSTR-1 is generally due on the 13th day of the month following the quarter.
Businesses should reconcile all three months before filing instead of waiting until the final day.
Form ADT-1 is used to intimate the Registrar of Companies regarding the appointment or reappointment of an auditor in applicable cases.
The important point is that ADT-1 does not have a universal 15 October deadline.
Under the applicable Companies Act framework, the notice of auditor appointment is generally required to be filed within 15 days of the meeting in which the auditor is appointed.
Therefore, if the auditor was appointed or reappointed at an AGM held on 30 September 2026, the corresponding filing date would generally fall on 15 October 2026.
Before filing, verify:
Persons responsible for collecting Tax Collected at Source should prepare the quarterly TCS statement in Form 27EQ for the July–September 2026 quarter.
Before filing, verify:
Employers covered under applicable employee-benefit laws should track PF and ESI compliances for September 2026.
Employers should reconcile:
Eligible taxpayers registered under the GST Composition Scheme should track Form CMP-08 for the July–September 2026 quarter.
CMP-08 is used for declaring the self-assessed tax liability and making the applicable tax payment.
GST taxpayers filing GSTR-3B monthly should complete their September 2026 return within the applicable timeline.
Before filing GSTR-3B, businesses should reconcile:
This is one of the most important updates for October 2026.
The Income Tax Department has confirmed that pursuant to Circular No. 07/2026, the due date for filing applicable audit reports for AY 2026–27 has been extended from:
30 September 2026 → 21 October 2026
The extension applies to the categories of taxpayers covered by the relevant provisions referred to in the CBDT circular.
For FY 2025–26 / AY 2026–27, applicable tax audit reports continue to use Forms 3CA, 3CB and 3CD, as applicable.
Businesses and professionals subject to tax audit should reconcile:
For applicable categories covered by the relevant CBDT announcement, the Income Tax Return filing deadline has also been extended from:
31 October 2026 → 21 November 2026
Businesses should separately verify whether the extension applies to their category.
The 22 October 2026 quarterly GSTR-3B due date generally applies to QRMP taxpayers whose principal place of business is in the first notified group.
The 24 October 2026 quarterly GSTR-3B deadline generally applies to taxpayers in the second notified group.
AOC-4 is an important annual MCA filing through which applicable companies file their financial statements and related documents with the Registrar of Companies.
However, 30 October 2026 should not be treated as the due date for every company.
Under the general framework, financial statements are filed within 30 days of the AGM.
Therefore, where an applicable company held its AGM on 30 September 2026, its AOC-4 filing would generally fall due on 30 October 2026.
Depending on applicability, the filing may include:
LLPs should track Form 8 – Statement of Account and Solvency for FY 2025–26.
For an LLP following the normal financial year ending 31 March 2026, Form 8 is generally due on 30 October 2026.
Before filing, LLPs should verify:
Quarterly TDS statements for the July–September 2026 quarter should be tracked for 31 October 2026, subject to the applicable provisions.
For TDS relating to salary payments.
For specified payments other than salary made to residents.
For specified payments made to non-residents.
Before filing, businesses should reconcile:
A structured compliance calendar can help businesses:
Businesses should avoid:
A Private Limited Company, LLP, composition taxpayer, QRMP taxpayer and monthly GST filer will not necessarily have the same compliance requirements.
Managing GST, income tax, payroll, ROC and LLP compliances while running a business can become difficult.
NeuSource supports startups and businesses with:
The objective is not simply to file forms, but to help businesses maintain an organised compliance framework as they grow.
October 2026 includes several important statutory deadlines for Indian businesses.
Key compliances during the month include TDS/TCS payments, GSTR-1, GSTR-3B, PF and ESI, CMP-08, tax audit reporting, AOC-4, LLP Form 8 and quarterly TDS statements.
One of the most significant current updates is the extension of the applicable AY 2026–27 Tax Audit Report deadline to 21 October 2026.
At the same time, businesses should remember that certain compliances — particularly Professional Tax, ADT-1 and AOC-4 — do not have one universal October deadline for every entity.
The safest approach is to identify the compliances applicable to your business and begin preparing before the statutory due date.
Disclaimer: This compliance calendar is intended for general informational purposes only. Applicability and due dates may vary based on entity type, state, turnover, registration status, AGM or appointment date and notifications issued by the relevant authorities. Businesses should verify the latest official notifications and obtain professional advice for entity-specific compliance requirements.
01 Oct
The internet offers opportunity, but only strategy builds success. Don't just exist online—dominate. Choose Neusource to craft your digital footprint and lead your business to its peak.